
The Pan-African Paradigm of Resource Dependency and Fiscal Sovereignty
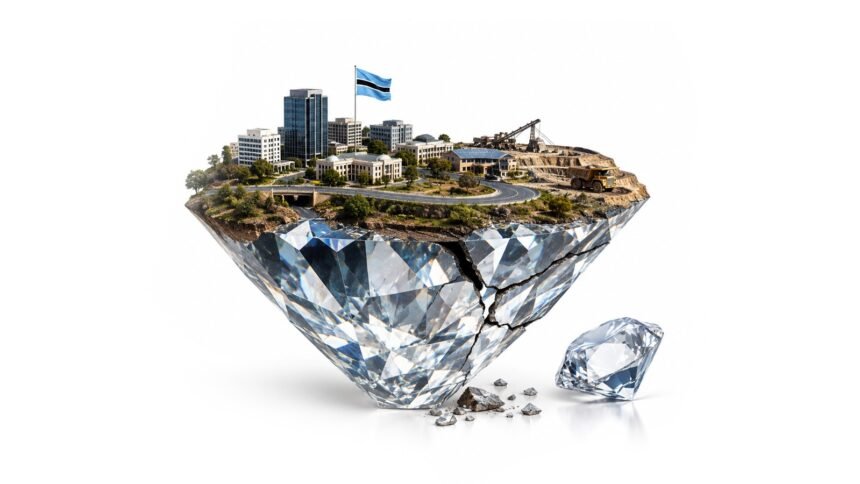
For decades, Botswana stood as the counter-example international institutions reached for whenever the phrase “resource curse” came up in discussions of African economies. This diamond-rich democracy translated mineral wealth into schools, roads, and one of the continent’s highest per-capita incomes. On Friday, Moody’s cut that same country’s sovereign rating for the second time in less than a year, to Baa2, leaving Botswana just two notches above junk status. The paradigm now in question is whether resource-based prosperity, however well-managed, can ever be structurally sovereign so long as roughly a third of national revenue and three-quarters of foreign exchange earnings trace back to a single commodity whose global price the country does not control. Botswana’s downgrade is not a story of mismanagement; it is a story of a diamond market disrupted by lab-grown competition and economic uncertainty, exposing a dependency built over fifty years of otherwise prudent governance. Reclaiming durable sovereignty from here will mean diversifying an economy that has, until now, had little structural reason to.
What Moody’s Actually Cut
Moody’s downgraded Botswana’s domestic- and foreign-currency long-term issuer ratings to Baa2 from Baa1, citing an expected deterioration in public finances, while shifting the outlook from negative to stable, a signal that the agency sees the immediate trajectory stabilizing even as the underlying rating falls. The timing is pointed: the downgrade landed just days after Finance Minister Ndaba Gaolathe told the public that Botswana expects a smaller budget deficit this fiscal year, helped by higher-than-anticipated central bank revenue and spending restraint. Moody’s cited weaker diamond-sector revenue, disappointing receipts from the Southern African Customs Union, a critical shared revenue pool for the region, and underwhelming returns from newly introduced tax measures as the drivers of fiscal weakening. The juxtaposition of a government insisting on improving finances and a ratings agency cutting anyway underscores how much of Botswana’s fiscal position now depends on variables largely outside domestic policy control.
The Diamond Market’s Structural Shift
Diamonds have long accounted for roughly a third of Botswana’s national revenue and three-quarters of its foreign exchange earnings. This concentration made sense when synthetic alternatives were a niche curiosity rather than a mainstream consumer choice. That has changed. The growing popularity of lab-grown diamonds, combined with broader economic uncertainty dampening luxury spending globally, has driven a prolonged downturn in the natural diamond market that Botswana’s economy has had no ready substitute for. This is not a cyclical dip Botswana can wait out with confidence; it is a structural repricing of the commodity that underwrote the country’s development model since independence, forcing a reckoning that governance quality alone cannot resolve.
The Anglo American Wildcard
Moody’s flagged a specific forward risk: that Botswana could face a further downgrade if it materially increases its stake in De Beers through debt-financed transactions, as Anglo American works to close a sale of the diamond giant by the fourth quarter of this year. Botswana already holds a significant stake in De Beers. It has periodically sought greater ownership of the company that mines much of its diamond wealth, an ambition rooted in the same sovereignty logic that drives resource nationalism across the continent, from Congo’s cobalt to Zambia’s copper. But Moody’s warning illustrates the bind: the debt Botswana would need to take on to deepen its ownership of De Beers could itself trigger the very credit deterioration the country is trying to avoid, making the pursuit of resource sovereignty fiscally self-defeating in the short term.
Reclaiming an Economy Beyond the Mine
Botswana’s downgrade should not be read as a verdict on four decades of comparatively disciplined governance, but as a warning about the ceiling that governance alone can reach when an economy remains this concentrated in one export. The stable outlook Moody’s attached to the new rating suggests confidence that Gaolathe’s fiscal measures can hold the line in the near term, but holding the line is not the same as building resilience. A more durable sovereignty for Botswana, one insulated from the next disruption to the diamond trade, synthetic or otherwise, will depend on diversification efforts that have been discussed for years and delivered unevenly. The diamond built Botswana’s development story; the question the country now faces is whether it can write the next chapter without leaning so heavily on the same stone.