
A Privatization Promise Made Under an IMF Program
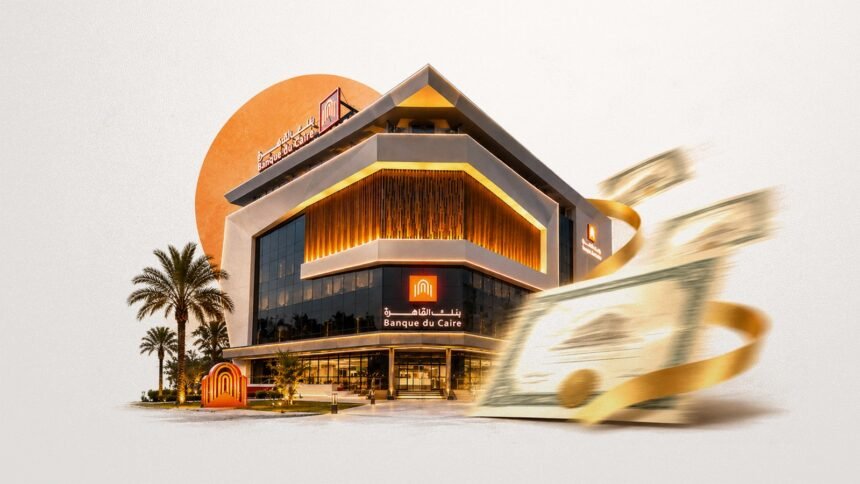
Thirty-six point three seven billion Egyptian pounds. That is roughly what Egypt raised on Monday, about $658 million, when it closed the initial public offering of Banque du Caire, the state-owned lender founded in 1952 and now the country’s third-largest public bank. It is one of the biggest asset sales Egypt has carried out in years, and it lands at a moment when international lenders are pressing Cairo to shrink the state’s footprint in the economy.
The mechanics were straightforward. Banque Misr, the bank’s majority shareholder and itself a state-owned institution, sold 6.86 billion shares, equal to 45 percent of Banque du Caire, at 5.30 Egyptian pounds each, according to the final offer announcement. At that price, the whole lender is valued at about 80.83 billion pounds, or roughly $1.46 billion.
The meaning is less simple. For Egypt, the sale is a test of whether a long-promised privatization drive can move from lists and timetables into completed deals that private and foreign investors are willing to fund. Across the continent, it joins a run of large listings this autumn that shows African issuers can still draw capital when the terms are clear.
Twenty Years on and Off
The offering was a long time coming. “This is an IPO that’s been more than 20 years on and off,” said Hussein Abaza, the bank’s chief executive, who listed the Covid-19 pandemic and the wars in Ukraine and Gaza among the hurdles that kept pushing it back. Each of those shocks hit Egypt’s foreign currency position and its stock market, and each made a large state sale harder to price.
Abaza presented the completed deal as a vote of confidence. “It’s a sign of confidence in the stock market itself. It’s also a sign that the country is serious about privatization,” he said. Prime Minister Moustafa Madbouly made a similar case, saying the listing had gone ahead despite regional tensions and underscored the government’s commitment to “continuing its program of state asset offerings, aiming to unlock greater value from public assets”.
Those regional tensions are not abstract. Egypt sits beside the war in Gaza, is weighing its role in the confrontation between Saudi Arabia and the Houthis in Yemen, and depends heavily on Red Sea and Suez Canal traffic. Selling a stake in a major bank against that backdrop required investors willing to take a long view.
Who Bought In
The anchor investors were development lenders rather than purely private funds. The International Finance Corporation, the World Bank’s private-sector arm, and the European Bank for Reconstruction and Development (EBRD) were among the top investors. The EBRD said in a statement that it had invested $100 million in Banque du Caire, acquiring a 6.9 percent share.
That mix cuts both ways. Development lenders bring credibility, governance demands and patient money, and their presence can reassure other buyers. But a privatization that relies heavily on multilateral institutions is not yet proof that commercial investors, at home or abroad, are ready to take large positions in Egyptian state assets on their own.
The structure also matters. The seller was Banque Misr, another state bank, so the proceeds move within the public banking system before they reach the wider budget. How the money is used, whether to strengthen Banque Misr’s own balance sheet or to ease the government’s financing needs, will shape how the sale is judged.
The IMF Timetable
The sale is part of a wider commitment. Egypt is advancing reforms under an International Monetary Fund program designed to increase private sector participation and reduce the state’s role in the economy. The government has previously said it plans to sell stakes in more than 30 state-owned companies under commitments linked to that support program.
Progress on that list has been slow, and Banque du Caire’s twenty-year path to market shows why. In June, authorities granted preliminary listings to four state-owned companies ahead of planned stock market offerings by May 2027. Monday’s result gives the government a working example to point to as those offerings approach, and a price benchmark for what investors will pay.
The deeper question in Egypt’s reform debate has been the place of state and military-linked companies across the economy, from construction to consumer goods. A bank listing does not answer that question, but it shows that sales can be completed when the asset is attractive, and the state is willing to cede a large minority stake.
A Continent of Big Listings
Egypt’s sale arrives in a busy season for African capital markets. Within the past week, Nigeria’s Dangote refinery closed what was billed as the largest public offering in African history, and the Nigerian fintech OPay listed in New York. Each deal has its own logic, but together they suggest that investors are willing to put money into African companies and assets when ownership, pricing, and disclosure are clear.
There is a difference, however. Nigeria’s listings were driven by a private industrialist and a private technology firm seeking growth capital. Egypt’s is a state selling part of what it owns, under external pressure, to raise money and signal reform. The first kind of listing expands a market; the second redistributes ownership within it. Both can deepen local exchanges, but only if the shares trade actively after the opening day.
Owning the Reform, Not Just Signing It
For Egypt, the real gain from privatization is not the headline dollar figure but who sets the pace and the purpose. Reforms written into lending agreements can feel like conditions imposed from outside, and they often stall when the pressure eases. A sale that leaves Egyptian pension funds, banks and retail savers holding meaningful stakes would tie more citizens to the performance of reformed state companies and give the reform a domestic constituency.
That is the measure to watch as the next four offerings approach. If Cairo can show that each sale strengthens competition, transparency, and local ownership, the privatization program becomes Egypt’s own economic strategy rather than a box ticked for its creditors. If the sales raise cash for debt service, the country will have sold assets without changing how its economy works.